Homeownership Benefits 2026: First-Time Buyer Programmes & 3% Down Payment
Navigating the complexities of purchasing a home can be daunting, but for those eyeing the US market in 2026, understanding available first-time buyer programmes offering up to 3% down payment assistance is crucial for achieving homeownership.
Por: [email protected] em 29 de julho de 2026
Última atualização em: 13 de agosto de 2026
Understanding the landscape of Homeownership Benefits 2026 is pivotal for aspiring homeowners, as numerous first-time buyer programmes in the US offer significant financial relief, including options for as little as 3% down payment assistance.
For many, the dream of owning a home in the United States often feels out of reach, especially with fluctuating market conditions and the significant hurdle of a down payment. However, for those looking towards 2026, there’s compelling news: a wealth of programmes designed to support first-time buyers, some even offering as little as 3% down payment assistance. This article delves into the crucial details of these Homeownership Benefits 2026, providing insider knowledge to help you navigate the path to securing your own property.
Understanding First-Time Buyer Programmes in 2026
The journey to homeownership can seem daunting, but a comprehensive understanding of available first-time buyer programmes in 2026 can significantly simplify the process. These initiatives are specifically designed to alleviate common barriers, such as the substantial upfront cost of a down payment, making property acquisition more accessible for a wider demographic. From federal government-backed options to state and local incentives, the landscape is rich with opportunities for aspiring homeowners.
Many individuals mistakenly believe that a 20% down payment is an absolute necessity, a misconception that often deters them from even exploring the possibility of buying. In reality, numerous programmes exist that dramatically reduce this requirement, bringing the dream of owning a home closer to reality. These programmes often come with specific eligibility criteria, but the benefits, including lower down payments and competitive interest rates, are well worth the effort of investigation.
Federal Government-Backed Programmes
The federal government plays a significant role in supporting first-time homebuyers through various agencies. These programmes are often the cornerstone of assistance for many, providing stability and security in the lending process.
FHA Loans: Backed by the Federal Housing Administration, FHA loans are popular for their low down payment requirement, often as little as 3.5%. They are accessible to individuals with lower credit scores, making them an excellent option for many first-time buyers.
VA Loans: Exclusively for eligible service members, veterans, and surviving spouses, VA loans offer the unparalleled benefit of no down payment requirement and no private mortgage insurance (PMI).
USDA Loans: Aimed at promoting homeownership in rural and designated suburban areas, USDA loans also offer zero down payment options for qualified applicants, alongside competitive interest rates.
Beyond these, various state and local housing authorities supplement federal efforts, often providing additional layers of assistance that can be stacked with federal programmes. These can include down payment grants, low-interest second mortgages, or tax credits, further reducing the financial burden on new homeowners. It’s essential to research what specific programmes are available in your target location, as eligibility and benefits can vary widely.
In conclusion, the array of first-time buyer programmes available in 2026 offers a robust support system for those looking to enter the housing market. By understanding the different types of assistance and their specific requirements, aspiring homeowners can strategically plan their path to property ownership, leveraging these benefits to overcome financial hurdles.
Navigating Down Payment Assistance: The 3% Solution
The concept of a 3% down payment has become a game-changer for many prospective homeowners, transforming what once seemed like an insurmountable financial barrier into an achievable goal. In 2026, several key programmes are making this low down payment a reality, significantly easing the entry point into the housing market for first-time buyers across the United States. Understanding these options is crucial for anyone hoping to leverage such substantial assistance.
While the traditional wisdom often dictates a 20% down payment to avoid private mortgage insurance (PMI) and secure better interest rates, the reality for many first-time buyers is that saving such a substantial sum can take years. The emergence of 3% down payment programmes directly addresses this challenge, accelerating the timeline to homeownership for countless individuals and families.
Key Programmes Offering 3% Down Payments
Several prominent programmes stand out for their 3% down payment offerings, each with its unique set of advantages and eligibility criteria. These include conventional loans with low down payment options, as well as specific initiatives designed to cater to a broader range of financial situations.
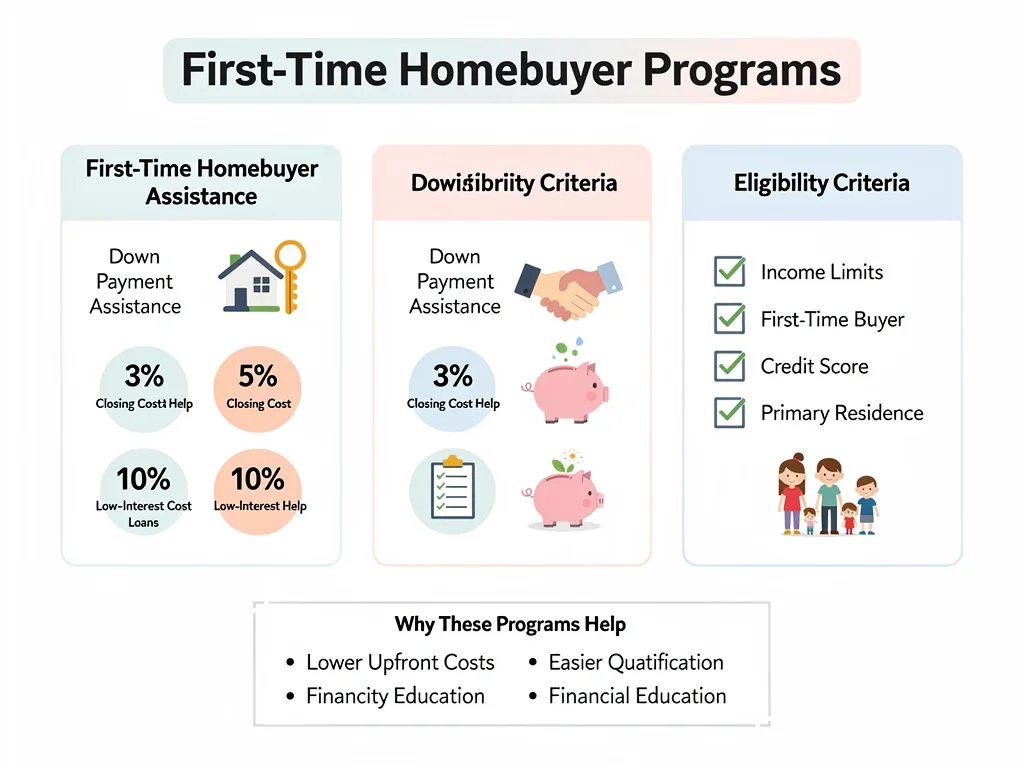
Fannie Mae’s HomeReady and HomePath: These conventional loan programmes allow for as little as 3% down payment for eligible borrowers, often with more flexible credit requirements than standard conventional loans. They are designed to help low-to-moderate-income borrowers and those in underserved communities.
Freddie Mac’s Home Possible: Similar to Fannie Mae’s offerings, Home Possible loans also feature a 3% down payment option, catering to a diverse group of buyers, including those with limited credit history or lower income.
State and Local Programmes: Many state housing finance agencies (HFAs) and local government initiatives offer their own down payment assistance programmes, which can often be combined with federal or conventional loans. These might come in the form of grants that don’t need to be repaid, or second mortgages with deferred payments or very low interest rates.
It is important to note that while a 3% down payment significantly reduces the upfront cost, borrowers will typically incur private mortgage insurance (PMI) on conventional loans if their down payment is less than 20%. However, the ability to get into a home sooner and begin building equity often outweighs the cost of PMI for many first-time buyers. Moreover, PMI can often be cancelled once sufficient equity is built.
The availability of 3% down payment options in 2026 represents a significant boon for aspiring homeowners. By carefully researching and comparing these programmes, first-time buyers can find the most suitable path to achieving their homeownership dreams, overcoming one of the most significant financial hurdles.
Eligibility Requirements and Application Process
Understanding the eligibility requirements and navigating the application process are critical steps for any first-time homebuyer seeking to utilise the Homeownership Benefits 2026. While specific criteria vary by programme, common threads run through most, focusing on financial stability, creditworthiness, and the applicant’s status as a first-time buyer. Being well-prepared for this stage can significantly streamline your journey to homeownership.
Each programme, whether federal, state, or local, will have its own set of rules. It is paramount to meticulously review these requirements to ensure you qualify before investing time and effort into the application. Common eligibility factors include income limits, credit score minimums, and participation in homebuyer education courses.
General Eligibility Criteria
While not exhaustive, the following points represent typical requirements encountered across various first-time buyer programmes:
First-Time Buyer Status: Generally defined as someone who has not owned a primary residence in the past three years. However, exceptions exist for certain circumstances, such as single parents or those who have only owned a property not permanently affixed to a foundation.
Income Limits: Many programmes are designed to assist low-to-moderate-income individuals and families. These limits are often tied to the area median income (AMI) and can vary significantly by location.
Credit Score: While some programmes, like FHA loans, are more forgiving with credit scores, most require a minimum score, typically in the mid-600s, to demonstrate financial responsibility.
Debt-to-Income Ratio (DTI): Lenders assess your DTI to ensure you can comfortably afford your mortgage payments alongside other financial obligations. A lower DTI is generally preferred.
Homebuyer Education: Many assistance programmes mandate completion of a homebuyer education course, which provides valuable information on the home-buying process, financial management, and homeowner responsibilities.
The application process typically begins with pre-qualification or pre-approval from a lender who participates in the specific programme you are interested in. This initial step helps you understand how much you can afford and identifies any potential roadblocks early on. Gathering necessary documentation, such as pay stubs, tax returns, and bank statements, is essential for a smooth application.
In essence, successfully navigating the eligibility requirements and application process for first-time buyer programmes in 2026 requires diligence and attention to detail. By understanding what is expected and preparing accordingly, aspiring homeowners can significantly increase their chances of securing the assistance needed to purchase their first home.
Beyond the Down Payment: Other Financial Benefits
While the allure of a low down payment is often the primary draw for first-time buyers, the Homeownership Benefits 2026 extend far beyond merely reducing upfront costs. Many programmes offer a suite of additional financial advantages that can significantly impact the long-term affordability and sustainability of homeownership. Understanding these supplementary benefits is key to maximising the value of available assistance.
These additional benefits can range from reduced interest rates and closing cost assistance to property tax exemptions and homeowner grants. By exploring these facets, first-time buyers can gain a more holistic view of the financial support available, making their homeownership journey not just possible, but also more financially sound in the long run.
Comprehensive Financial Support
The layers of financial support available to first-time buyers are designed to address various aspects of homeownership, ensuring that once a home is purchased, it remains affordable.
Lower Interest Rates: Some programmes offer preferential interest rates, which can translate into significant savings over the life of the loan. Even a small reduction in the interest rate can reduce monthly payments substantially.
Closing Cost Assistance: Closing costs can amount to several thousands of pounds, representing another significant hurdle for first-time buyers. Many programmes offer grants or low-interest loans specifically to cover these costs, reducing the out-of-pocket expenses at closing.
Mortgage Credit Certificates (MCCs): An MCC allows homeowners to claim a portion of their mortgage interest as a tax credit, rather than a deduction. This direct reduction in tax liability can provide an ongoing financial boost, effectively lowering the cost of homeownership annually.
Homeowner Education and Counselling: Beyond financial aid, many programmes provide access to free or low-cost homebuyer education and counselling. This equips new homeowners with the knowledge and tools to manage their finances, maintain their property, and navigate the responsibilities of homeownership effectively.
These benefits are not always universally available and often depend on the specific programme, location, and individual eligibility. Therefore, thorough research into state and local housing authorities, as well as federal programmes, is crucial. Combining multiple assistance options, where permissible, can further amplify the financial advantages for first-time buyers.
In conclusion, the financial benefits associated with first-time buyer programmes in 2026 are multifaceted, extending well beyond the initial down payment. By leveraging these comprehensive support systems, aspiring homeowners can achieve their dream with greater financial security and confidence, setting a solid foundation for their future.
The Role of Credit Scores and Financial Health
A robust credit score and overall sound financial health are cornerstones for accessing the most advantageous Homeownership Benefits 2026. While some programmes are more lenient, a strong financial profile significantly broadens the range of available options, often leading to better interest rates and more favourable loan terms. Understanding how your credit score and financial habits impact your eligibility is therefore paramount.
Lenders and programme administrators assess your financial health to gauge your ability to manage debt and make timely mortgage payments. A higher credit score signals lower risk, which in turn can unlock more competitive loan products and assistance programmes. Conversely, a lower score might limit options or necessitate higher interest rates.
Improving Your Financial Standing
For those looking to enhance their financial health in preparation for homeownership, several strategies can be employed:
Monitor Your Credit Report: Regularly checking your credit report for errors and discrepancies is crucial. Correcting inaccuracies can quickly boost your score.
Pay Bills on Time: Payment history is the most significant factor in credit scoring. Consistently paying all bills on time demonstrates reliability.
Reduce Debt: Lowering your credit utilisation ratio (the amount of credit you use versus the amount available) by paying down existing debts can positively impact your score.
Avoid New Debt: Refrain from opening new credit accounts or taking on significant new loans in the months leading up to a mortgage application, as this can temporarily lower your score.
Build a Savings Cushion: Beyond the down payment, having an emergency fund and reserves for closing costs and initial home maintenance is vital. This demonstrates financial stability to lenders.
Even if your credit score isn’t perfect, there are still pathways to homeownership. Programmes like FHA loans are specifically designed for individuals with less-than-perfect credit, offering a more accessible route. However, even with these options, demonstrating an effort to improve financial habits will be beneficial.
Ultimately, investing time in improving your credit score and cultivating sound financial habits will yield substantial dividends when applying for first-time buyer programmes in 2026. A strong financial foundation not only enhances your chances of approval but also ensures a more secure and affordable homeownership experience.
State and Local Initiatives: A Hidden Gem
While federal programmes form a vital backbone of support, state and local initiatives often serve as hidden gems, offering unique and highly beneficial Homeownership Benefits 2026 tailored to specific regional needs. These programmes can provide crucial additional layers of assistance, often complementing federal options and significantly enhancing the affordability of purchasing a home within a particular community. Exploring these localized opportunities is an essential step for any aspiring homeowner.
The vast array of state and local programmes reflects the diverse housing markets and economic conditions across the United States. From urban revitalization efforts to rural development incentives, these initiatives are designed to address specific challenges and promote sustainable homeownership in their respective areas. Overlooking these resources would mean missing out on potentially significant financial aid.
Types of State and Local Assistance
The nature of state and local assistance can vary widely, encompassing a broad spectrum of financial and educational support:
Down Payment Assistance (DPA) Programmes: Many states and cities offer DPA in the form of grants (which do not need to be repaid) or second mortgages with deferred payments or forgivable terms. These can often be stacked with federal or conventional loans, further reducing the upfront cost.
First-Time Homebuyer Tax Credits: Some regions provide tax credits, such as Mortgage Credit Certificates (MCCs), which allow homeowners to claim a portion of their mortgage interest as a direct tax credit, reducing their annual tax liability.
Affordable Housing Programmes: Local housing authorities often manage programmes that facilitate the purchase of affordable housing units, sometimes offering below-market interest rates or subsidies for specific income brackets.
Revitalization and Community Development Loans: In areas targeted for revitalization, special loans or grants might be available to encourage homeownership, often with favourable terms or property improvement incentives.
Homebuyer Education and Counselling: State and local entities frequently provide free or low-cost educational resources, guiding first-time buyers through the complexities of the home-buying process and homeowner responsibilities.
It is important to remember that eligibility for these programmes is typically tied to living or purchasing a home within the specific state, county, or city offering the assistance. Income limits, property value caps, and specific borrower requirements are common and must be carefully reviewed. Engaging with a local housing counsellor or a lender familiar with regional programmes is highly advisable.
In essence, state and local initiatives are powerful tools for first-time buyers in 2026, providing tailored support that can make a substantial difference in achieving and sustaining homeownership. By diligently researching and leveraging these localized opportunities, aspiring homeowners can unlock a broader range of financial benefits.
Future Outlook and Strategic Planning for 2026
As we look towards 2026, the landscape of homeownership, particularly for first-time buyers, continues to evolve. Strategic planning, coupled with a keen understanding of anticipated market trends and programme developments, will be essential for leveraging the available Homeownership Benefits 2026. Proactive preparation can significantly enhance your chances of successfully purchasing a home and making the most of the assistance on offer.
The housing market is dynamic, influenced by economic indicators, interest rate fluctuations, and policy changes. Staying informed about these factors, alongside understanding the long-term implications of your home purchase, is crucial for making a sound investment. Strategic planning involves not just securing a loan but also ensuring the long-term affordability and growth potential of your property.
Key Considerations for 2026 Homebuyers
To navigate the 2026 housing market effectively, consider the following strategic points:
Market Research: Continuously monitor local housing market trends, including property values, inventory levels, and average time on market. This will help you identify opportune times and locations for purchasing.
Interest Rate Forecasts: Keep an eye on economic forecasts regarding interest rates. Even small changes can impact your monthly mortgage payments and overall affordability. Locking in a favourable rate is a key strategic move.
Programme Updates: Down payment assistance programmes and first-time buyer initiatives are subject to change. Regularly check for updates from federal, state, and local housing authorities to ensure you have the most current information.
Long-Term Financial Planning: Beyond the initial purchase, consider your long-term financial goals. How will homeownership affect your savings, retirement planning, and other investments? Develop a budget that accounts for all home-related expenses, including maintenance, property taxes, and insurance.
Professional Guidance: Engage with experienced real estate agents, mortgage lenders, and financial advisors who specialise in first-time buyer programmes. Their expertise can provide invaluable insights and guidance throughout the process.
Furthermore, consider the energy efficiency of potential homes. With growing environmental consciousness and rising utility costs, a home with good insulation, energy-efficient appliances, and potentially solar panels could offer significant long-term savings and increased property value. Some programmes even offer incentives for purchasing energy-efficient homes.
In summary, strategic planning for homeownership in 2026 involves more than just finding a property and securing a loan. It requires a comprehensive approach that encompasses market awareness, financial foresight, and diligent research into available programmes. By adopting such a strategy, first-time buyers can confidently embark on their homeownership journey, making informed decisions that lead to lasting financial stability and personal satisfaction.
Key Aspect
Brief Description
3% Down Payment
Programmes like Fannie Mae and Freddie Mac offer low down payments, making homeownership more accessible.
Federal Programmes
FHA, VA, and USDA loans provide significant benefits, including low or no down payment options.
State & Local Aid
Additional grants, tax credits, and DPA are available regionally, often stackable with federal loans.
Financial Health
Good credit scores and financial planning are crucial for securing the best loan terms and benefits.
Frequently Asked Questions About 2026 Homeownership Benefits
What exactly qualifies as a ‘first-time buyer’ for these programmes?▼
Generally, a ‘first-time buyer’ is someone who has not owned a primary residence in the last three years. However, some programmes offer exceptions for single parents, individuals who have only owned a non-permanent structure, or those who have been displaced due to natural disasters. It’s crucial to check specific programme definitions.
Can I combine multiple down payment assistance programmes?▼
Yes, in many cases, you can combine a federal loan programme (like FHA, VA, or USDA) with state or local down payment assistance. This ‘stacking’ of programmes can significantly reduce your out-of-pocket expenses. Always consult with a lender experienced in these programmes to understand the permissible combinations.
Are there income limits for the 3% down payment programmes?▼
Many 3% down payment programmes, particularly those from Fannie Mae (HomeReady) and Freddie Mac (Home Possible), do have income limits. These are typically set as a percentage of the Area Median Income (AMI) for the location where you intend to buy. Limits vary by region, so checking local guidelines is essential.
What credit score do I need to qualify for these benefits?▼
Credit score requirements vary by programme. FHA loans often accept scores as low as 580 with a 3.5% down payment, while conventional loans with 3% down typically require scores in the mid-600s or higher. VA and USDA loans are more flexible, often focusing on overall financial health rather than a strict score.
Will interest rates affect the availability of these homeownership benefits in 2026?▼
While interest rates don’t directly affect the existence of these programmes, they can impact affordability and demand. Higher rates might make monthly payments more challenging, even with down payment assistance. It’s wise to monitor rate forecasts and understand how they interact with programme benefits when planning your purchase.
Conclusion
The prospect of homeownership in 2026 is brighter than ever for first-time buyers, thanks to a robust array of programmes offering significant financial assistance, including options for as little as 3% down payment. By diligently researching federal, state, and local initiatives, understanding eligibility criteria, and proactively managing personal finances, aspiring homeowners can confidently navigate the complexities of the housing market. These comprehensive Homeownership Benefits 2026 are designed not just to open the door to property ownership, but to foster long-term financial stability and transform the dream of owning a home into a tangible reality for many across the United States.
I'm a journalist with a passion for creating engaging content. My goal is to empower readers with the knowledge they need to make informed decisions and achieve their goals.