Comparing US Robo-Advisors: Performance & Fees for 2026
Comparing US Robo-Advisors: Performance and Fees for 2026 (Average 0.25% AUM) reveals a dynamic landscape where technology-driven investment platforms offer accessible, diversified portfolio management with competitive costs, often around 0.25% AUM.
Por: Maria Eduarda em 22 de julho de 2026
Última atualização em: 13 de agosto de 2026
The landscape of US robo-advisors in 2026 is characterised by evolving technology and competitive pricing, offering automated investment solutions with an average asset under management (AUM) fee of approximately 0.25%.
Navigating the complex world of investments can feel daunting, but the rise of robo-advisors has democratised access to sophisticated financial planning. For those in the United States looking to optimise their portfolios in 2026, understanding the nuances of US robo-advisors 2026, particularly their performance and fee structures, is paramount. These automated platforms promise intelligent, diversified investing, often at a fraction of the cost of traditional human advisors. This guide will delve into what makes these platforms tick, offering a comprehensive comparison to help you make an informed decision for your financial future.
Understanding the Robo-Advisor Landscape in 2026
The year 2026 marks a significant evolution in the robo-advisory space, with platforms offering increasingly sophisticated algorithms and personalised investment strategies. These digital advisors leverage technology to manage portfolios, rebalance assets, and even provide tax-loss harvesting, all with minimal human intervention. This automation often translates into lower costs and greater accessibility for a broad range of investors.
The core appeal of robo-advisors lies in their ability to remove emotional biases from investing decisions and provide consistent, disciplined portfolio management. They typically build diversified portfolios based on an investor’s risk tolerance, financial goals, and time horizon. This approach helps ensure that investments remain aligned with long-term objectives, even during market volatility.
The Evolution of Automated Investing
Robo-advisors have come a long way since their inception, moving beyond simple ETF portfolios to incorporate more complex financial planning tools. In 2026, many platforms offer features like goal-based planning, access to human financial advisors for specific needs, and even socially responsible investing (SRI) options. This expansion makes them viable for a wider array of investors, from beginners to those with more complex financial situations.
Sophisticated Algorithms: Advanced algorithms now consider more variables, leading to more tailored portfolio recommendations.
Hybrid Models: Many platforms integrate human advisors, offering a blend of automation and personalised guidance.
Enhanced Features: Beyond basic portfolio management, features like automatic rebalancing, tax-loss harvesting, and goal tracking are standard.
Accessibility: Lower minimum investment requirements make professional money management accessible to almost everyone.
The landscape in 2026 is competitive, pushing providers to innovate and refine their offerings. This competition ultimately benefits the consumer, driving down fees and enhancing service quality. Investors now have more choices than ever when it comes to entrusting their financial future to a digital platform, requiring careful consideration of each option’s unique strengths.
Comparing Performance: What to Look For
When evaluating US robo-advisors 2026, performance is undeniably a critical factor. However, it’s crucial to understand that past performance is not indicative of future results, and direct comparisons can be complex due to varying investment strategies, risk profiles, and market conditions. Instead, focus on a robo-advisor’s methodology, transparency, and how well its strategy aligns with your personal investment philosophy.
A good starting point is to examine how a robo-advisor constructs its portfolios and what asset classes it utilises. Most robo-advisors use exchange-traded funds (ETFs) to build diversified portfolios across various asset classes, including equities, fixed income, and sometimes real estate or commodities. The specific ETFs chosen, their expense ratios, and the overall asset allocation strategy will significantly impact performance.
Key Performance Indicators
Beyond raw returns, consider other metrics that provide a more holistic view of a robo-advisor’s effectiveness. These include risk-adjusted returns, which measure how much return an investment generates for the amount of risk taken, and consistency over different market cycles. A platform that performs well in both bull and bear markets demonstrates a robust strategy.
Risk-Adjusted Returns: Essential for understanding performance relative to the level of risk assumed.
Diversification Strategy: How well the portfolio is spread across different asset classes and geographies.
Tax-Loss Harvesting Effectiveness: For taxable accounts, this feature can significantly boost after-tax returns.
Rebalancing Frequency: Regular rebalancing helps maintain the target asset allocation and manage risk.
It’s also beneficial to look at client testimonials and independent reviews, although these should be taken with a grain of salt. Focus on reviews that discuss the platform’s responsiveness, ease of use, and clarity of reporting. Ultimately, the ‘best’ performing robo-advisor is one that helps you achieve your financial goals efficiently and comfortably, aligning with your risk tolerance and ethical considerations.
Fee Structures: The Average 0.25% AUM and Beyond
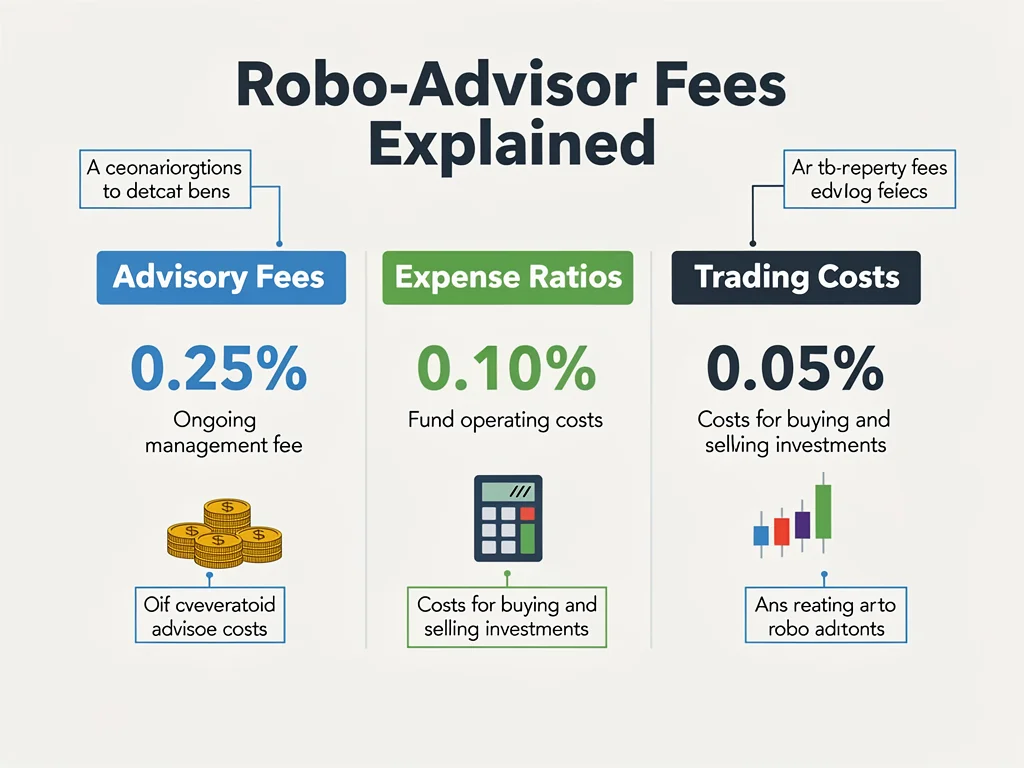
One of the most attractive aspects of US robo-advisors 2026 is their competitive fee structures, which are typically significantly lower than those of traditional financial advisors. The average asset under management (AUM) fee often hovers around 0.25%, making professional investment management accessible to a broader audience. This percentage is usually charged annually on the total value of the assets you have invested with the platform.
While 0.25% AUM is a common benchmark, it’s important to delve deeper into what this fee covers and if there are any additional costs. Some robo-advisors may offer tiered pricing, where the AUM fee decreases as your invested assets grow. Others might have a flat monthly fee for smaller balances, which can sometimes be more cost-effective depending on your investment size.
Unpacking the Total Cost of Ownership
Beyond the headline AUM fee, investors must consider the total cost of ownership. This includes the expense ratios of the underlying ETFs in your portfolio. While robo-advisors often select low-cost ETFs, these fees are separate from the advisory fee and can add a small percentage to your overall costs. Transaction fees for buying and selling securities are generally absorbed by the robo-advisor, but it’s always wise to confirm.
Advisory Fees: The main fee, usually a percentage of AUM, covering portfolio management.
ETF Expense Ratios: Fees charged by the fund providers, embedded within the ETF’s price.
Transaction Costs: Typically minimal or non-existent, but worth verifying for clarity.
Premium Service Fees: Additional costs for features like access to human advisors or advanced planning tools.
Understanding these different layers of fees is crucial for an accurate comparison. A robo-advisor with a slightly higher AUM fee might offer superior tax-loss harvesting or more comprehensive financial planning tools that could offset the difference in fees through enhanced after-tax returns or added value. Always read the fine print and ensure you understand every potential charge before committing.
Top US Robo-Advisors to Consider in 2026
As we look at the landscape of US robo-advisors 2026, several platforms consistently stand out for their innovative features, competitive fees, and strong performance. While individual preferences will vary, a few key players have established themselves as leaders in the automated investing space. These platforms cater to a diverse range of investors, from those just starting out to experienced individuals seeking sophisticated tools.
Fidelity Go, Vanguard Digital Advisor, Charles Schwab Intelligent Portfolios, Betterment, and Wealthfront are among the most prominent. Each offers a unique blend of services, investment strategies, and fee structures. For instance, some may excel in tax optimisation, while others might provide more extensive access to human advisors or a wider range of investment options, including socially responsible portfolios.
Key Players and Their Unique Offerings
Each leading robo-advisor has carved out a niche, offering distinct advantages that appeal to different investor profiles. For example, some platforms might offer zero advisory fees but rely on revenue from underlying fund expense ratios, while others might have a transparent AUM fee model with premium features.
Fidelity Go: Known for its low minimums and strong integration with Fidelity’s broader ecosystem, often appealing to existing Fidelity clients.
Vanguard Digital Advisor: Leverages Vanguard’s reputation for low-cost index funds, offering highly competitive expense ratios and straightforward portfolio construction.
Charles Schwab Intelligent Portfolios: Unique for its zero advisory fee model, though it does allocate a portion of the portfolio to cash, which can impact returns.
Betterment: A pioneer in the space, offering robust tax-loss harvesting, goal-based planning, and a hybrid option with human advisors.
Wealthfront: Popular among tech-savvy investors, providing advanced features like Smart Beta, direct indexing, and a strong focus on automation and customisation.
When selecting a robo-advisor, it’s not just about finding the cheapest option. It’s about finding the best fit for your financial goals, risk tolerance, and the level of guidance you desire. Consider the minimum investment requirements, the range of account types supported (e.g., taxable, IRA, Roth IRA), and the availability of customer support. A thorough comparison will ensure you choose a platform that truly serves your long-term financial interests.
The Impact of Market Conditions on Robo-Advisor Performance
The performance of US robo-advisors 2026, like any investment, is inherently linked to prevailing market conditions. While their algorithmic approach aims to mitigate emotional biases and maintain discipline, no investment strategy is entirely immune to market downturns or fluctuations. Understanding how different market environments can impact robo-advisor performance is crucial for setting realistic expectations.
During bull markets, diversified portfolios managed by robo-advisors tend to perform well, tracking broad market indices. Their automatic rebalancing features ensure that portfolios remain aligned with target allocations, preventing over-exposure to rapidly appreciating assets and locking in gains. Conversely, during bear markets, even the most well-diversified portfolios will likely experience declines, though the automated risk management can help cushion the impact.
Navigating Volatility with Automation
One of the key advantages of robo-advisors during volatile periods is their adherence to a predetermined investment strategy. This prevents impulsive decisions driven by fear or greed, which can often lead to suboptimal outcomes for individual investors. The systematic approach to rebalancing and asset allocation ensures that the portfolio remains on track, even when human emotions might dictate otherwise.
Emotional Detachment: Algorithms remove human biases, preventing panic selling or speculative buying.
Diversification Benefits: Spreading investments across various asset classes helps reduce overall portfolio risk.
Tax-Loss Harvesting: Can be particularly beneficial in down markets by offsetting capital gains with losses.
Investors should view their robo-advisor’s performance over the long term, rather than focusing on short-term fluctuations. Market cycles are a natural part of investing, and the value of a robo-advisor often shines in its ability to consistently apply a sound investment strategy through various economic conditions. Regular reviews of your financial goals and risk tolerance with your chosen platform can also help ensure your portfolio remains appropriate for changing life circumstances.
Choosing the Right Robo-Advisor for Your Needs
Selecting the ideal US robo-advisor 2026 goes beyond just comparing performance and fees; it requires a thoughtful assessment of your individual financial situation, goals, and preferences. What works best for one investor might not be suitable for another. A holistic approach involves evaluating several factors, from the level of human interaction you desire to the types of investments you wish to hold.
Begin by defining your investment goals clearly. Are you saving for retirement, a down payment on a house, or a child’s education? Your time horizon and risk tolerance for each goal will influence the recommended portfolio. For instance, a long-term retirement goal might warrant a more aggressive portfolio than a short-term savings objective.
Factors to Consider Beyond Fees and Performance
While fees and performance are crucial, they are not the only considerations. The user experience of the platform, the quality of customer support, and the availability of educational resources can significantly enhance your investing journey. A platform that is easy to navigate and provides clear, understandable reporting can make a big difference in your comfort level and engagement.
Investment Goals: Align the robo-advisor’s capabilities with your specific financial objectives.
Risk Tolerance: Ensure the platform’s risk assessment and portfolio construction match your comfort level.
Minimum Investment: Check if the platform’s minimums are compatible with your starting capital.
Customer Support: Evaluate the availability and responsiveness of their support channels.
Additional Features: Consider tax-loss harvesting, goal planning, and access to human advisors.
Ethical Investing Options: If socially responsible investing is important, look for platforms offering SRI portfolios.
Ultimately, the best robo-advisor is one that not only helps you achieve your financial goals but also provides peace of mind through transparent operations and reliable support. Take the time to explore demo accounts if available, read reviews from various sources, and don’t hesitate to contact their customer service with any questions you may have before making a commitment.
The Future of Robo-Advisors: Trends for 2026 and Beyond
The landscape of US robo-advisors 2026 is not static; it’s continually evolving with technological advancements and changing investor demands. Looking ahead, several key trends are set to shape the future of automated investing, potentially offering even more sophisticated and personalised services. These developments promise to further integrate financial planning into everyday life, making it more intuitive and comprehensive.
One significant trend is the increasing adoption of artificial intelligence (AI) and machine learning (ML) to refine portfolio optimisation and predictive analytics. This will allow robo-advisors to offer more dynamic and adaptive strategies, potentially reacting to market shifts with even greater precision. Personalisation will also deepen, moving beyond generic risk assessments to truly individualised financial roadmaps.
Emerging Technologies and Service Enhancements
The integration of AI and ML is expected to lead to more nuanced advice and potentially better risk management. These technologies can process vast amounts of data to identify patterns and make more informed investment decisions. Furthermore, the push towards holistic financial wellness means robo-advisors will likely expand their offerings to include budgeting tools, debt management, and even estate planning, creating a one-stop shop for financial health.
Hyper-Personalisation: AI-driven insights will lead to highly customised investment strategies and financial advice.
Holistic Financial Planning: Expansion into broader financial services like budgeting, debt management, and insurance.
Enhanced User Experience: More intuitive interfaces and seamless integration with other financial apps.
Advanced Risk Management: ML algorithms will offer more sophisticated risk assessment and mitigation techniques.
Cryptocurrency Integration: A growing number of platforms may offer access to digital assets within diversified portfolios.
The future of robo-advisors also points towards greater integration with other financial services, creating a more interconnected and seamless financial ecosystem. This could include partnerships with banks, credit unions, and insurance providers, offering a truly comprehensive financial management experience. As technology continues to advance, robo-advisors are poised to play an even more central role in helping individuals achieve their financial aspirations.
Key Aspect
Brief Description
Average AUM Fee
Most US robo-advisors charge around 0.25% annually on assets under management, significantly lower than traditional advisors.
Performance Metrics
Evaluate risk-adjusted returns, diversification, tax-loss harvesting efficiency, and rebalancing strategies.
Total Cost
Consider advisory fees, ETF expense ratios, and any additional costs for premium features to determine true expenditure.
Future Trends
Expect increased AI/ML integration, hyper-personalisation, and holistic financial planning services.
Frequently Asked Questions About US Robo-Advisors
What is a robo-advisor and how does it work?▼
A robo-advisor is a digital platform that provides automated, algorithm-driven financial planning services with little to no human supervision. It typically works by assessing your risk tolerance and financial goals to build and manage a diversified portfolio of ETFs, rebalancing it automatically.
Are robo-advisors suitable for all investors?▼
While highly accessible and cost-effective, robo-advisors are best suited for investors comfortable with automated processes and seeking diversified, long-term growth. Those with highly complex financial situations or a strong preference for direct human interaction might find traditional advisors more appropriate, or opt for hybrid models.
How do robo-advisor fees compare to traditional financial advisors?▼
Robo-advisor fees are significantly lower, averaging around 0.25% of AUM in 2026, plus underlying ETF expense ratios. Traditional advisors typically charge 1% or more of AUM, or hefty hourly/flat fees, making robo-advisors a more budget-friendly option for many.
Can robo-advisors help with tax-loss harvesting?▼
Yes, many leading robo-advisors offer automated tax-loss harvesting, a strategy that sells investments at a loss to offset capital gains and potentially reduce taxable income. This feature can significantly enhance after-tax returns, especially for investors with taxable accounts.
What security measures do robo-advisors have in place?▼
Reputable robo-advisors employ robust security measures, including encryption, two-factor authentication, and FDIC/SIPC insurance to protect client assets and personal information. They are regulated by the SEC and adhere to strict compliance standards, offering a secure environment for your investments.
Conclusion
In 2026, the landscape of US robo-advisors offers a compelling blend of accessibility, technological sophistication, and cost-effectiveness for investors. With average AUM fees around 0.25%, these platforms continue to democratise professional financial management, making it easier for individuals to build diversified portfolios aligned with their long-term goals. By carefully comparing performance metrics, understanding the full scope of fees, and considering personal financial needs, investors can confidently select a robo-advisor that provides a robust and reliable path to financial success. The ongoing evolution of AI and machine learning promises an even more personalised and integrated financial future, solidifying the role of robo-advisors as a cornerstone of modern investing.
A journalism student and passionate about communication, she has been working as a content intern for 1 year and 3 months, producing creative and informative texts about decoration and construction. With an eye for detail and a focus on the reader, she writes with ease and clarity to help the public make more informed decisions in their daily lives.